The Dividend Stock That Keeps Raising Its Payout No Matter What the Market Does
How lengthy does an organization want to lift its yearly dividend cost till you are satisfied its dividend progress is virtually bulletproof? Twenty years? Maybe 30? Would 70 years do the trick?
As outrageous as these sounds, a handful of companies have actually done it (and they’re nonetheless doing so). And one among these few names is a high prospect proper now following the inventory’s 14% pullback from its February peak. That’s Procter & Gamble (P.G. 0.80%).
Here’s a better have a look at why it might belong in your portfolio, significantly proper now.
Image supply: Getty Images.
Procter & Gamble is greater than you may notice
You’ve nearly actually heard of the firm, however are you conscious of simply how broad and entrenched its product portfolio is?
Procter & Gamble is the title behind manufacturers like Tide laundry detergent, Gillette razors, Dawn dishwashing liquid, Crest toothpaste, Pampers diapers, and Bounty paper towels, amongst others. Most of their merchandise are leaders of their respective classes, if solely as a result of they have been round ceaselessly and have had loads of time to change into the most well-liked, out-of-habit buy. That’s additionally why the firm’s the largest title in the consumer goods enterprise, driving gross sales of $84.3 billion final fiscal yr and turning $16.1 billion of that into internet earnings.

Today’s Change
(-0.80%)$-1.14
Current Price
$141.57
Key Data Points
Market Cap
$330B
Day’s Range
$141.20 – $143.40
52wk Range
$137.62 – $170.99
Volume
7M
Avg Vol
10M
Gross Margin
50.88%
Dividend Yield
3.01%
Ohits internet progress was modest, to be clear, as is normally the case for this big, multifaceted firm. There’s solely a lot progress to be made in the well-saturated shopper staples enterprise.
Investors do not personal a stake in P&G at the beginning for progress, nonetheless. While they’re going to actually get some in the event that they grasp on to it lengthy sufficient, this inventory’s dividend pedigree is its chief promoting function.
As famous, P&G’s per-share payout has now been elevated for 70 consecutive years and continues to be going. And by greater than slightly. The annual improve introduced in April was a 3% enchancment on the prior payout, capping off a 10-year streak the place the dividend cost grew at a mean yearly fee of 4.8%.
But there is a a lot deeper, philosophical argument for getting and holding a place in Procter right here.
Built powerful
This is not to recommend the firm can merely breeze via any challenges. Things get powerful for it, too. For occasion, since inflation turned commonly unwieldy starting in 2022, greater than as soon as has the firm reported disappointing quarterly income ensuing from worth hikes it had little alternative however to impose.
It responded because it ought to, with every little thing from job cuts to extra aggressive innovation. But a few of its challenges are largely out of its management. High oil pricesfor instance, might shave as a lot as $1 billion off this yr’s backside line.
In the grand scheme of issues, although, Procter & Gamble enjoys an arguably unfair benefit over its rivals. That’s its sheer measurement.
This size-based benefit manifests in a number of methods. Perhaps the most essential one, nonetheless, is that P&G is solely in a position to spend extra on advertising and marketing and advertising than rivals like Clorox and Colgate-Palmolive.
For perspective, Procter spent $9.2 billion on promoting final fiscal yr, versus Colgate-Palmolive’s $2.7 billion and Clorox’s typical $800 million. In a enterprise the place the repetition of a advertising and marketing message issues, Procter & Gamble’s opponents simply cannot afford to maintain up.
Procter’s measurement additionally helps in one other often-overlooked manner. That’s the proven fact that its product lineup is so essential to retailers. Not solely are P&G’s high quality merchandise comparatively straightforward to promote to shoppers, however retailers know Procter & Gamble will promote their very own items, driving foot visitors to shops the place shoppers are apt to purchase one thing else whereas there. This offers the firm vital leverage when negotiating wholesale pricing or placement on a retailer’s cabinets.
In different phrases, Procter & Gamble’s acquired true endurance.
Not proper for everybody, however an ideal possibility for some
Again, it is not a progress inventory by any means. P&G shares have underperformed the S&P 500 (^GSPC 1.24%) for the higher a part of the previous 10 years, in reality, with or with out reinvested dividends.
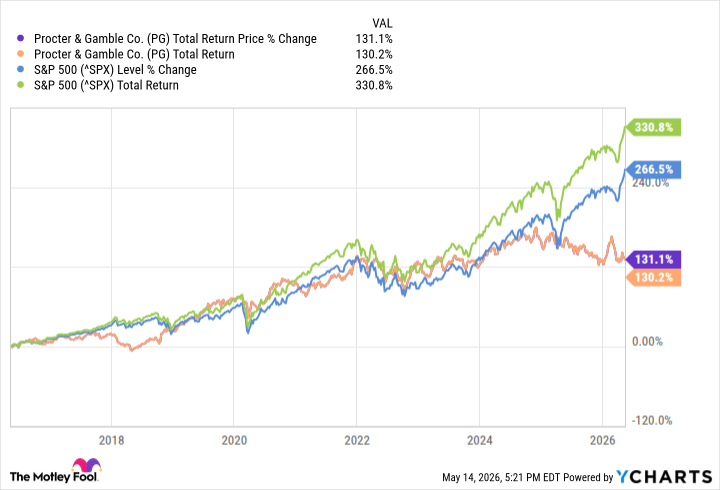
PG Total Return Price information by YCharts
Still, Procter’s carried out its job as an income-producing holding. It’s dished out in the order of $14.00 price of rising per-share dividends throughout this stretch, sustaining a decent yield of between 2.3% and three.2% for many of this time.
Perhaps extra noteworthy proper now — below the darkish clouds of what seemingly might flip into extra pronounced financial weak spot — discover on the chart that PG shares are likely to carry out higher when the general market would not. If, for some cause, traders begin worrying about AI stocks’ wild valuations and all of the sudden search security, a well-proven Procter & Gamble is one among the first names they’re going to doubtless flip to.
Bottom line? Don’t make it sophisticated. It’s not a horny inventory to personal. However, P&G is actually a dependable one — particularly for income-seeking traders. You can plug into it whereas its forward-looking dividend yield is a stable 3%.