

Microsoft Stock Is Down 22%, but Here’s Why It Could Soar After April 29
The inventory market is off to a risky begin to 2026. The Nasdaq-100 expertise index was down by as a lot as 12% from its peak in March, solely to recuperate all of its losses and hit a brand new file excessive in April. Investors have been attempting to cost within the potential financial impacts of the wild swings in oil costs, brought on by the geopolitical battle between the US and Iran.
But Wall Street’s consideration will quickly be on the working efficiency of a few of America’s largest expertise firms. On April 29, Microsoft (MSFT 0.62%) will launch its monetary outcomes for its fiscal 2026 third quarter (ended March 31), which can embody invaluable updates on synthetic intelligence (AI) services such because the Copilot digital assistant, and the Azure cloud platform.
Microsoft inventory is at present down 22% from its file excessive, but here is why the April 29 report could possibly be a really bullish catalyst.
Image supply: Getty Images.
Copilot adoption will likely be front-and-center
AI chatbots are a dozen proper now, so it is unlikely all of them will survive over the long run. However, Copilot has a definite benefit, as a result of it is being deployed into Microsoft’s current software program merchandise that collectively serve billions of customers world wide already.
Copilot is accessible at no cost within the Windows working system, the Bing search engine, and the Edge web browser, but it will also be added to enterprise variations of the 365 productiveness suite (which incorporates Word, Excel, Outlook, and extra) for an extra subscription charge. This is a large monetary alternative for Microsoft, as a result of firms world wide already pay for over 400 million 365 licenses for his or her staff, and each one in every of them is a candidate for the Copilot improve.
But as of Dec. 31, companies had solely bought 15 million Copilot for 365 licenses, representing a modest penetration charge of simply 3.7%. On the plus facet, that determine was up 160% 12 months over 12 months, and a few of the utilization metrics counsel eleven companies begin utilizing Copilot, they have a tendency to introduce it to extra of their staff over time.
Microsoft is probably going to supply an replace on Copilot adoption on April 29, and traders will most likely wish to see extra triple-digit proportion progress given the comparatively low base license quantity.

Today’s Change
(-0.62%)$-2.61
Current Price
$420.18
Key Data Points
Market Cap
$3.1T
Day’s Range
$417.12 – $423.13
52wk Range
$355.67 – $555.45
Volume
198K
Avg Vol
38M
Gross Margin
68.59%
Dividend Yield
0.82%
Azure was doubtless Microsoft’s progress engine (once more) in Q3
Over the previous 4 quarters, Microsoft spent $118 billion to construct information facilities that home 1000’s of specialised chips from Nvidia and different suppliers. It rents this infrastructure to companies by its Azure cloud platform, they usually use it to develop AI fashions and software program for their very own functions.
Azure income grew at a blistering tempo of at the very least 39% 12 months over 12 months in every of the primary two quarters of fiscal 2026, making it Microsoft’s fastest-growing phase. Azure could possibly be rising even quicker, but Microsoft merely cannot construct information facilities rapidly sufficient to satisfy demand. In reality, as of Dec. 31, the corporate had a staggering $625 billion order backlog from prospects who had been ready for extra infrastructure to come back on-line.
However, one of many causes Microsoft inventory offered off over the previous few months is that 45% of that backlog (or $281 billion) was attributable to ChatGPT creator OpenAI alone. In February, the startup introduced some unhealthy information: It will spend solely $600 billion on computing capability by 2030 throughout all suppliers, decreasing its earlier forecast of $1.4 trillion. As a end result, Microsoft’s order backlog is perhaps overstated, which is one thing the corporate will most likely clear up on April 29.
However, demand for computing energy would exceed provide for the foreseeable future even when we eliminated OpenAI from the image completely, so Azure doubtless delivered extraordinarily quick progress but once more through the third quarter.
Microsoft’s valuation leaves loads of room for upside
Based on Microsoft’s trailing-12-month earnings of $15.98 per share and its inventory worth of $422.79 on the market shut on Friday, April 17, its price-to-earnings (P/E) ratio is simply 26.4. That is a steep low cost to its five-year common of 32.9, and it is also decrease than the P/E of the Nasdaq-100which is at present 32.4.
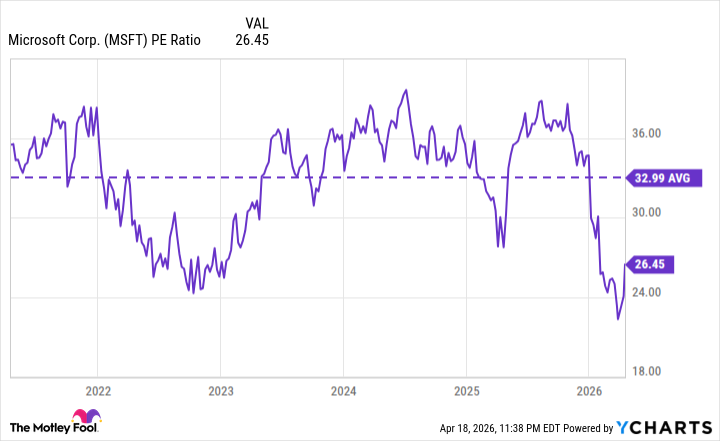
MSFT PE Ratio information by YCharts
As a end result, Microsoft stock appears undervalued proper now, but I do not assume that may stay the case for lengthy. If the corporate alleviates a few of the uncertainty surrounding its cloud order backlog on April 29, whereas demonstrating sturdy Azure income progress and strong Copilot adoption, traders may really feel extra assured about shopping for its inventory.
In phrases of potential upside, the inventory must climb by 24% only for its P/E ratio to commerce in step with its five-year common of 32.9, so there could possibly be sturdy returns on the desk for traders who purchase in forward of the upcoming earnings report. However, it is essential to keep up a long-term view, as a result of traders may reap a lot greater rewards as Microsoft’s AI companies mature over the following 5 years or so.